You find a home you love in Martin County. The price looks possible, and the payment on the listing seems close to your budget. Before you picture moving day, there is one question worth answering: What would this particular home actually cost you each month?
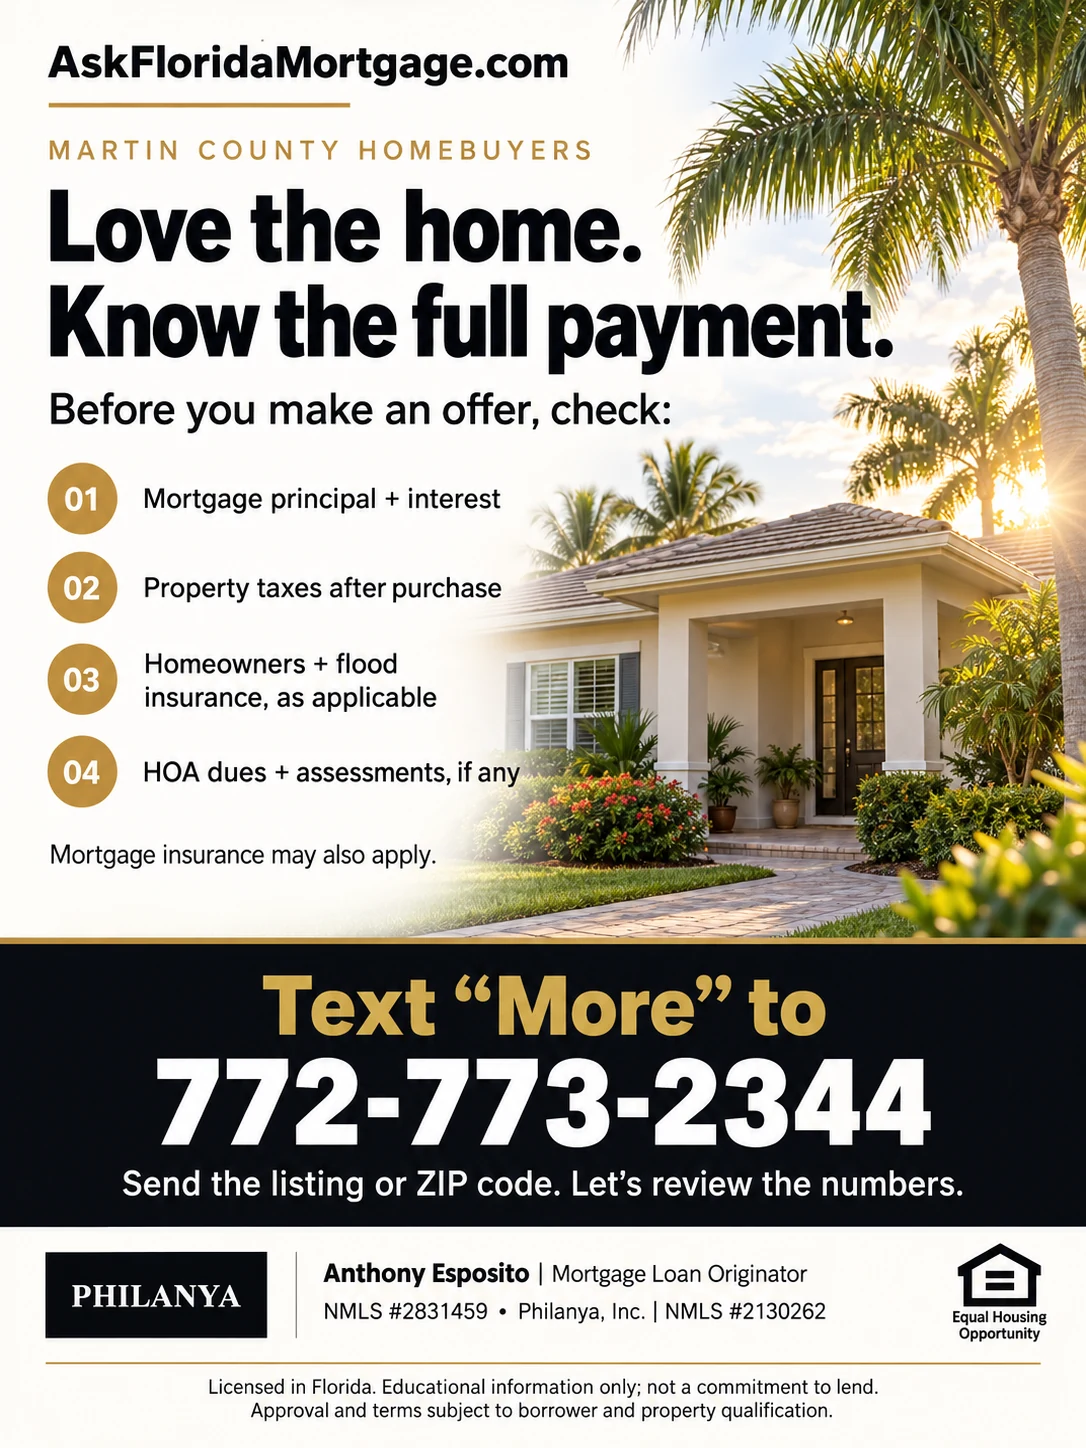
A useful homebuying budget includes mortgage principal and interest, property taxes, homeowners insurance, any applicable flood and mortgage insurance, and association charges. Some of those expenses may be paid separately from your mortgage. Together, they determine whether the home fits your life.
Whether you are searching in Stuart, Palm City, Jensen Beach, Hobe Sound, Indiantown, or another Martin County community, start with the property’s full cost—not just its asking price.
Have a home in mind? Text “More” to 772-773-2344. Send the listing or ZIP code, and let’s review which numbers need a closer look.
What should your Martin County mortgage payment estimate include?
A mortgage calculator can be a starting point, but its answer depends on the information entered. Review these items before relying on a payment estimate:
The CFPB advises buyers to add taxes, insurance, applicable mortgage insurance, and association dues to principal and interest when estimating the monthly cost of a specific home. Read the CFPB’s mortgage-calculator guidance.
Your personal budget also needs room for utilities, maintenance, repairs, and savings. A lender’s qualification calculation and your comfortable household budget serve different purposes.
| Cost | What to check for the home you are considering |
|---|---|
| Principal and interest | Loan amount, interest rate, term, and whether the payment structure can change |
| Property taxes | An estimate reflecting your purchase and potential exemptions, rather than simply the seller’s current bill |
| Homeowners insurance | A property-specific quote with the coverage and deductibles explained |
| Flood insurance | Whether it is required or appropriate for the property, and the separate premium if applicable |
| Mortgage insurance | Whether the proposed loan requires it and how it affects upfront and monthly costs |
| HOA or condominium dues | Current dues, payment frequency, and what the association actually covers |
| Assessments and other property charges | Amount, due dates, payment responsibility, and whether a charge is already included elsewhere |
1. Estimate property taxes for your purchase
One of the most consequential numbers to check is the tax estimate. A seller may have exemptions or assessment protections that do not carry over to you in the same way.
The Martin County Property Appraiser specifically warns buyers against relying on the seller’s current taxes as the amount they will owe after purchasing. A change in ownership can trigger reassessment and a higher tax bill. See the Property Appraiser’s buyer warning.
Use the county’s Property Tax Estimator, selecting the appropriate homestead or non-homestead path. Ask about your own eligibility for exemptions and portability rather than assuming the seller’s treatment applies.
For a newly built home, check whether the displayed tax history reflects a vacant lot or an earlier stage of construction. An old tax figure may not represent the completed home.
Ask before making an offer: “Does this payment use a tax estimate for me as the buyer, or the seller’s historical bill?”
2. Get insurance numbers for the actual address
Avoid making your decision from a generic insurance placeholder. Ask a licensed insurance professional for a quote on the home you are considering and review the coverage, deductibles, and any information still needed before coverage can be bound.
Useful questions include:
Most homeowners policies do not cover flood damage; flood insurance is separate coverage. FEMA explains flood insurance.
Martin County’s Property Information Lookup provides address-based information including flood zones, land use, and utilities. Use it to start your research, then confirm financing and coverage requirements with the relevant professionals. A ZIP code alone cannot settle those questions.
Ask before making an offer: “Is this insurance number based on this property, and what could still change it?”
- What roof and property information does the insurer need?
- Are inspections or supporting reports needed for the quote?
- What are the applicable hurricane and other deductibles?
- Does the home require a separate flood policy for financing?
- What coverage should be considered even if the lender does not require it?
3. Read beyond the HOA or condo fee
A home with a lower asking price can still require a larger monthly budget if association charges are higher. Conversely, a higher fee may cover some expenses you would otherwise pay separately. You need to know what is included before comparing two homes.
Request the current dues, payment schedule, association budget, and information about existing or proposed assessments. For a condominium, ask early about the building documents your lender will need to review.
Separate recurring monthly dues from a one-time assessment or installment obligation. Confirm who is responsible for a charge under the purchase agreement. If an assessment appears on a tax bill, make sure it is not counted twice in your estimate.
Ask before making an offer: “What will I pay the association, what does it cover, and are there additional charges to plan for?”
4. Compare two homes using the same worksheet
When comparing a Stuart condo with a Palm City house—or two homes in the same neighborhood—use the same categories for both. Keep the loan assumptions consistent unless you are intentionally comparing different financing options.
Label every unconfirmed figure as an estimate. Annual expenses divided by 12 help with budgeting; they do not necessarily describe when a bill will be due.
Closing costs, prepaid expenses, and initial escrow funding also deserve a separate review. The Loan Estimate is an important document for understanding proposed mortgage costs once you apply. An informal worksheet does not replace it.
| Item to compare | Home A | Home B |
|---|---|---|
| Asking price and planned down payment | Enter your figures | Enter your figures |
| Mortgage principal and interest | Estimated amount | Estimated amount |
| Property taxes after purchase | Annual estimate divided by 12 | Annual estimate divided by 12 |
| Homeowners and applicable flood insurance | Annual premiums divided by 12 | Annual premiums divided by 12 |
| Monthly mortgage insurance, if applicable | Confirm with loan review | Confirm with loan review |
| HOA or condo dues | Monthly equivalent | Monthly equivalent |
| Other recurring assessments | Include without double counting | Include without double counting |
| Total ongoing housing cost | Add the applicable costs | Add the applicable costs |
| Cash needed at closing | Compare separately | Compare separately |
| Savings remaining after closing | Compare separately | Compare separately |
Martin County communities and ZIP codes: use the address to confirm
This countywide guide is for buyers across Stuart, Palm City, Jensen Beach, Ocean Breeze, Hobe Sound, Jupiter Island, Indiantown, Sewall’s Point, Port Salerno, and Martin County’s unincorporated areas.
ZIP codes describe postal delivery, not exact county or municipal boundaries. The broader Martin County real-estate directory includes the following 17 associated ZIP codes. The table separates commonly used local delivery codes, PO-box codes, and additional regional codes so they are not mistaken for 17 separate Martin County neighborhoods. View the ZIP-code directory.
The five PO-box codes are identified separately in Martin Health’s community assessment. For a current mailing ZIP, use the USPS address lookup. For a home’s county and property details, use official property records.
The practical takeaway: send the listing or street address when you have one. It gives us a stronger starting point than a ZIP code by itself.
| Area or postal association | ZIP codes | How to use them |
|---|---|---|
| Stuart area | 34994, 34996, 34997 | Start an address-specific search; a Stuart mailing address does not necessarily mean a home is inside city limits |
| Palm City | 34990 | Confirm the property location and associated expenses |
| Jensen Beach area | 34957 | Check the county for the particular address, especially near county boundaries |
| Hobe Sound area | 33455 | Confirm the property’s location and jurisdiction |
| Indiantown area | 34956 | Check the address and property type rather than making assumptions from the postal name |
| Local PO-box mailing codes | 33475, 34958, 34991, 34992, 34995 | Mailing references, not residential search areas or proof of a home’s location |
| Additional regional codes listed with Martin County | 33438, 33458, 33469, 33478, 34974 | These are also associated with neighboring areas; verify the individual parcel’s county before applying county-specific guidance |
Before you start touring, set two limits
Set a comfortable total monthly housing budget and a minimum savings cushion you want to retain after closing. Those two limits can help you avoid focusing exclusively on the largest loan you might qualify for.
If you are still preparing, the 90-day renter-to-buyer guide can help you organize the next steps. When you are ready for a mortgage review, the Florida preapproval guide explains what to gather.
If upfront funds are the obstacle, read the Florida buyer-assistance guide. Assistance must be checked against current funding and your eligibility; it should not be assumed simply because a property is in Martin County.
Love the home. Know the full payment.
A home should fit more than an approval amount. It should fit the way you want to live after the keys are yours.
Text “More” to 772-773-2344. Send the listing or ZIP code and tell me what you are trying to decide. I can help you identify the mortgage numbers to review and the property expenses that still need verification.
No application is needed to ask an initial question. Please keep Social Security numbers, bank records, and other sensitive documents out of ordinary text messages; requested application documents belong in the secure mortgage workflow.
Prefer email? anthony.esposito@philanya.com. Ready to begin online? Use askangel.ai/anthony.esposito.
Anthony Esposito | Mortgage Loan Originator | NMLS #2831459 Philanya, Inc. | NMLS #2130262 Licensed in Florida. Equal Housing Opportunity. Educational information only; not a commitment to lend. Loan approval, program eligibility, rates, terms, and assistance availability are subject to change and borrower/property qualification. Tax and insurance estimates require verification with the appropriate professionals. NMLS Consumer Access.
Local homebuying questions
Frequently asked questions
How much house can I afford in Martin County?
The answer depends on your income, debts, available funds, loan terms, and the specific property’s expenses. Start with a monthly budget that leaves room for your other obligations, then review qualification and closing funds separately.
Will my property taxes stay the same as the seller’s?
Do not assume they will. Review an estimate for your purchase with the Martin County Property Appraiser’s resources and ask about your own exemption eligibility.
Are HOA dues included in the mortgage payment?
They are often paid separately to the association. They still affect your overall budget and mortgage review. Check the payment estimate so the dues are included in your total housing cost without being counted twice.
Can I know whether flood insurance is needed from the ZIP code?
No. Review the specific address, flood information, lender requirements, and available coverage with the appropriate professionals.
Can I text before I apply?
Yes. Start with your question, the listing or ZIP code, and your approximate timeline. We can discuss the information needed for a useful next step before you begin an application.
Primary sources
Program details can change. These links are the starting point for current verification.