You do not need to be ready to tour homes this weekend to begin. Starting online can give you a clearer buying range and a plan—then you can shop when the timing feels right.
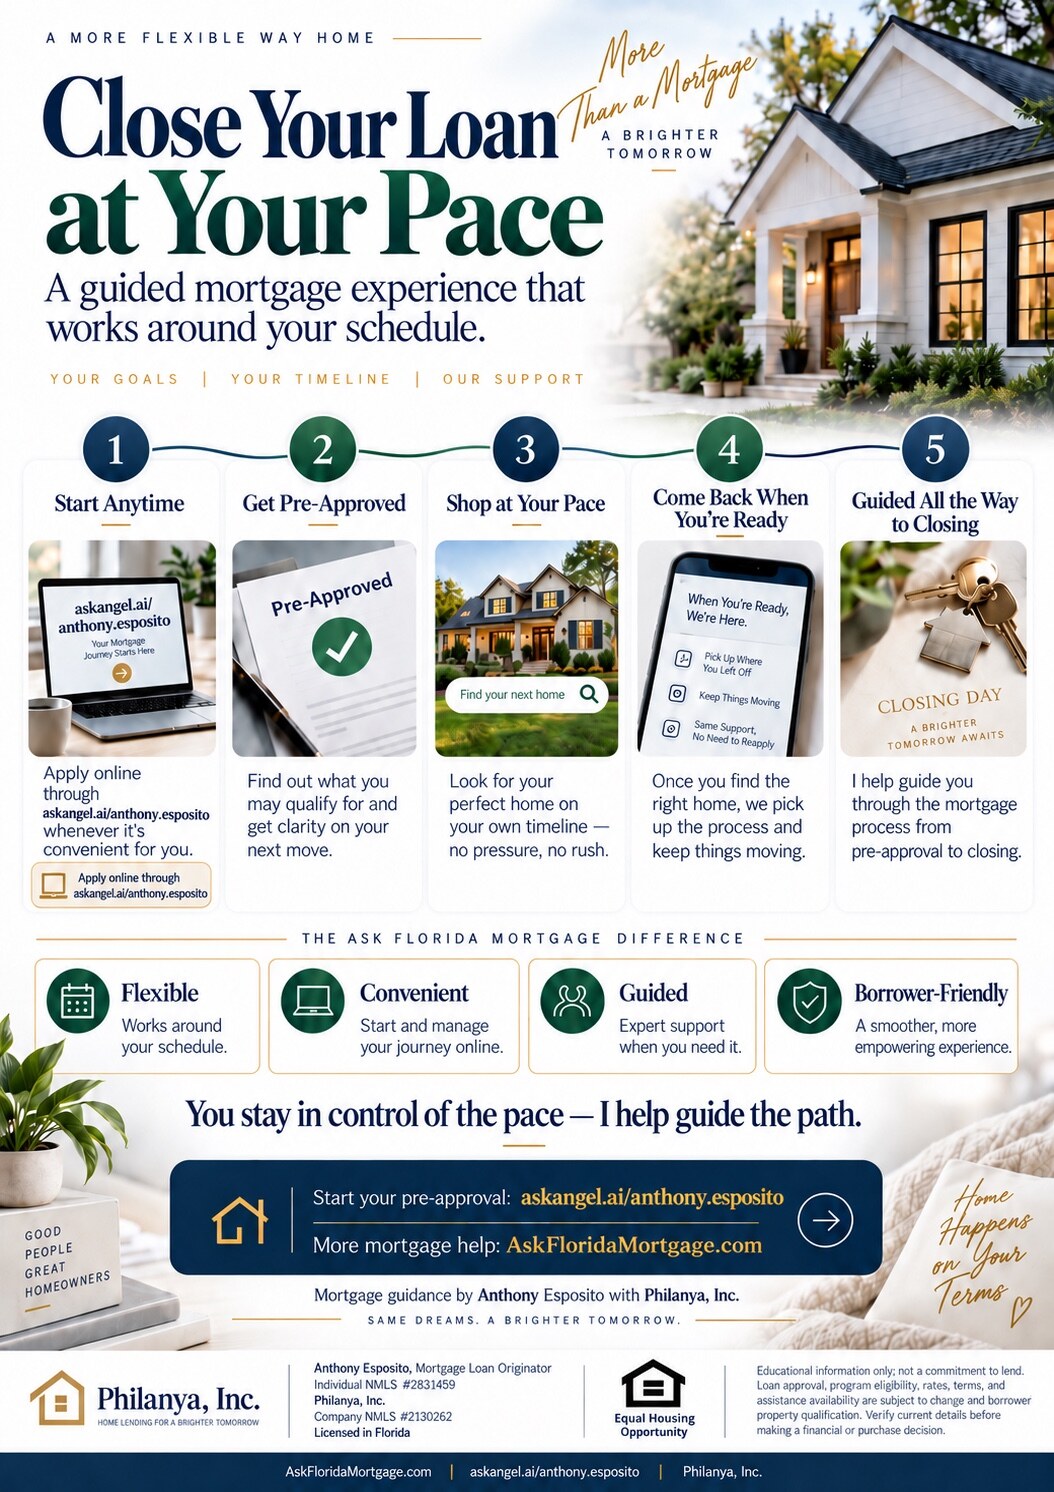
What “at your pace” really means
Buying a home does not have to begin with pressure to make an offer. You can start by learning what your income, debts, credit profile, funds, and goals may support. If the numbers make sense, you can prepare before you actively shop instead of trying to solve everything after finding a house.
The flexibility is mainly before you are under contract. After a seller accepts your offer, the purchase agreement, financing contingency, appraisal, insurance, title work, underwriting conditions, and scheduled closing date create real deadlines. A calmer start gives you a better chance to meet those deadlines later.
The five-step online mortgage path
- 1
Start online when it is convenient
Open Anthony’s AskAngel experience, review the consent prompts, and begin sharing the information needed for a mortgage conversation. You can start without arranging a phone call first.
- 2
Build a realistic preapproval picture
Your income, employment, credit, monthly debts, available funds, planned occupancy, and loan goals help determine which paths deserve a closer review.
- 3
Shop for the right home—not merely the highest price
Use the reviewed numbers to focus on a total housing payment and cash requirement that fit your life. The maximum qualifying amount is not automatically a comfortable budget.
- 4
Come back before the offer
When you find a home, reconnect so the property, price, taxes, insurance, HOA dues, program, estimated payment, and timing can be checked before you depend on an older scenario.
- 5
Move from preapproval to final loan approval
The borrower file and the specific property still go through documentation, appraisal, title, insurance, underwriting, and final closing requirements. Anthony helps coordinate the mortgage side through that process.
What happens when you use Anthony’s Angel AI link
Anthony’s AskAngel link opens a personalized Angel AI experience connected to Anthony Esposito. It provides an online starting point for the mortgage conversation and can bring Anthony into the process when personal guidance is needed.
Anthony’s public Angel partner page also identifies Philanya, Inc. as the mortgage company and provides access to Apply Now, down-payment assistance information, credit tools, a loan calculator, common loan-program resources, and Anthony’s contact information.
Use the mortgage application workflow for application information or requested documents. The Ask Florida Mortgage contact form is for general questions and should not be used to send Social Security numbers, bank information, tax returns, identification, or other sensitive application material.
What to have ready for a useful preapproval review
- Legal name, contact information, current address, and planned property use
- Employment history and gross income for each borrower
- Approximate monthly payments for credit cards, vehicles, student loans, and other debts
- Available funds for down payment, closing costs, and reserves
- Permission and identifying information required for a credit review
- Recent income, asset, tax, or other documents requested for your specific situation
- Your preferred Florida area, price range, timing, and comfortable monthly housing payment
Preapproval is a strong planning step—not final approval
A preapproval is based on the information reviewed at that time. It is not a commitment to lend, a guaranteed interest rate, or final approval of a borrower, property, or loan program. The home still has to meet applicable appraisal, title, insurance, condition, occupancy, and program requirements.
Your position can also change if your income, employment, credit, debts, assets, down payment, interest rate, property, or program changes. Before opening new credit, changing jobs, moving large amounts of money, or making a major purchase, ask how the change could affect the mortgage file.
Why starting before you feel rushed can help
- You have time to correct missing or inconsistent documents.
- You can compare an estimated total payment with your real household budget.
- You can discuss possible down-payment assistance without assuming the funds or eligibility are guaranteed.
- You can learn which property types or price ranges may create issues before touring homes.
- You can choose whether to shop now or work a preparation plan first.
Florida mortgage questions
Frequently asked questions
Can I start a mortgage preapproval online in Florida?
Yes. Anthony’s AskAngel link provides an online starting point connected to Anthony. A lender still must review the required borrower information and documents before issuing or updating a preapproval.
Does mortgage preapproval guarantee final loan approval?
No. Final approval depends on the complete borrower file, the selected property, appraisal, title, insurance, program requirements, underwriting, and any remaining conditions.
Do I have to buy a home immediately after getting preapproved?
No. You can use the review to decide whether to shop, prepare, or wait. Ask when your credit review and documents may need to be refreshed because lender requirements and personal circumstances can change.
What should I avoid changing while I shop for a home?
Avoid making major financial changes without checking first. New debt, large purchases, job changes, new credit accounts, or unexplained movement of funds can affect qualification or create additional documentation needs.
When should I reconnect after finding a home?
Reconnect before relying on a payment or writing an offer. The price, taxes, insurance, HOA dues, property type, loan program, rate environment, and contract dates should be checked against your current file.
Primary sources
Program details can change. These links are the starting point for current verification.