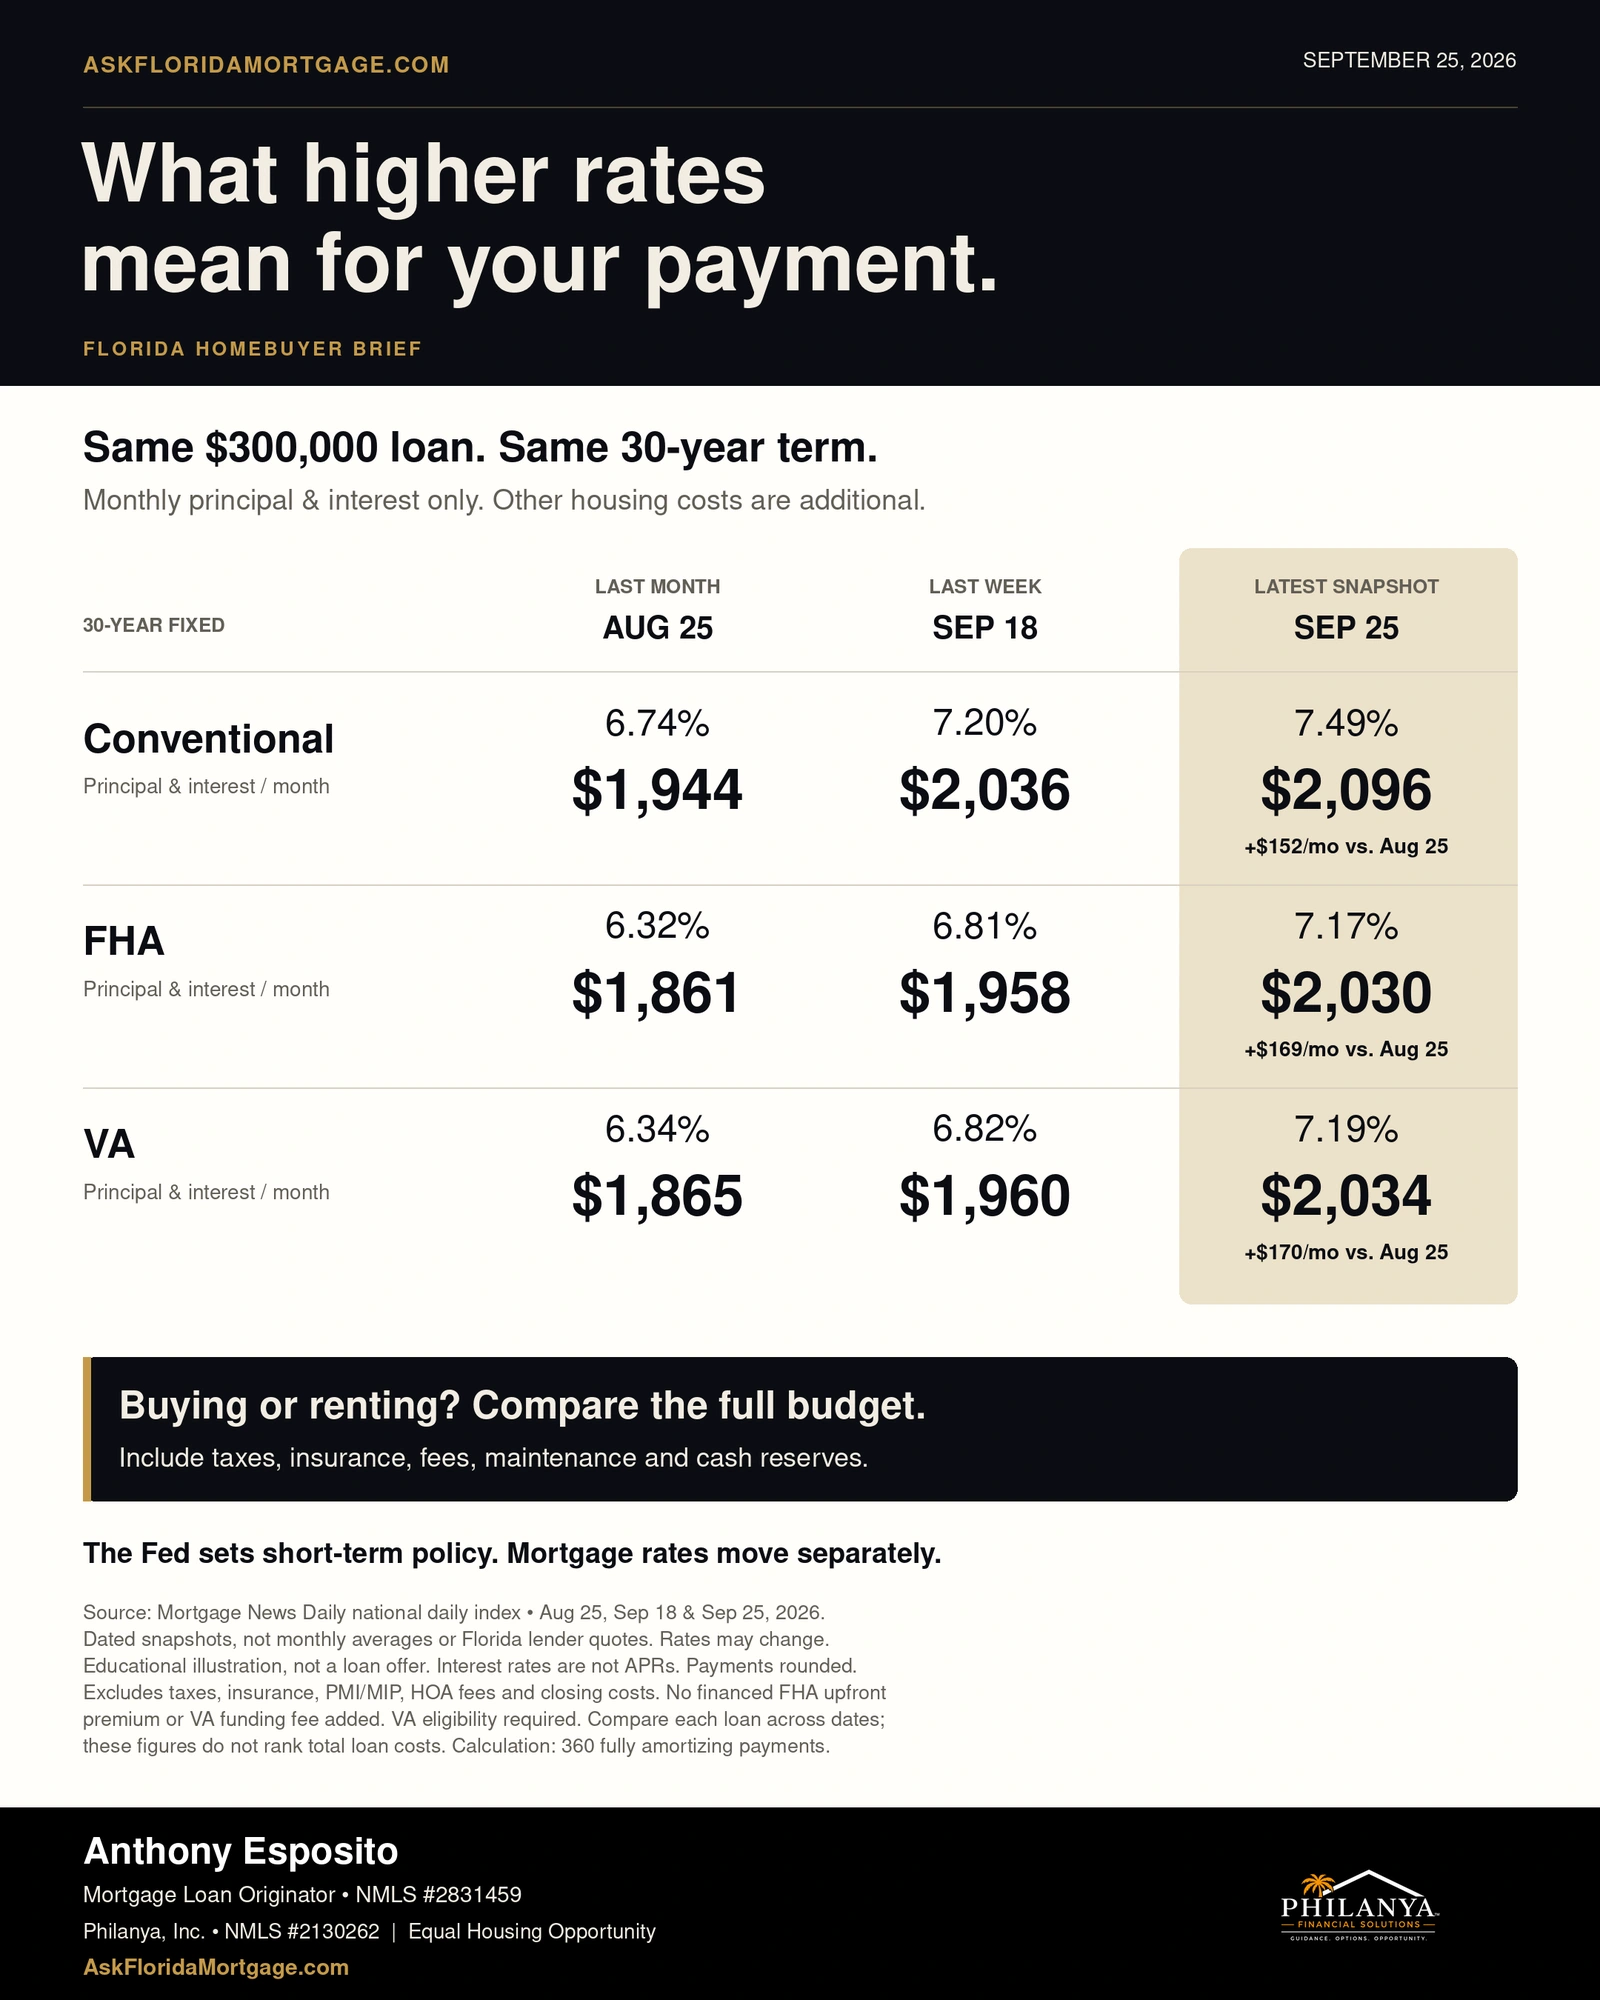
Updated September 25, 2026. This comparison uses Mortgage News Daily’s September 25 snapshot, with September 18 for last week and August 25 for last month. These are individual daily observations, not weekly or monthly averages, and are national benchmarks—not personalized Florida lender quotes. Rates can change after this snapshot.
If higher-rate headlines have you wondering whether to keep renting, start with the payment difference and your full budget. A higher rate can make a home harder to afford. It does not, by itself, settle whether buying or renting is the better choice for you.
The Fed increase is confirmed. This article explains the available data and your budget choices without predictions about future rates, rents or home prices.
What did the Federal Reserve actually increase?
On September 16, 2026, the Federal Reserve raised the federal funds target range by 0.25 percentage point, to 3.75%–4.00%. Its statement cited elevated inflation. That is a change in the Fed’s short-term policy rate; it is not a new interest rate assigned to every mortgage. Read the official FOMC statement.
Mortgage pricing also reflects bond-market conditions, investor expectations and lender-specific pricing. It can move before or after a Fed announcement. August 25 predates the Fed decision; September 18 and 25 follow it. The difference between these dates is not a measurement of the Fed decision’s isolated effect. How mortgage rates move.
Last month, last week and the September 25 mortgage rate snapshot
We use Mortgage News Daily’s daily index for all three dates and loan types: conventional 30-year fixed, FHA 30-year fixed and VA 30-year fixed. Keeping one source and consistent loan categories makes the changes easier to compare. View the dated index history.
“Last month” means August 25; “last week” means September 18. Neither column is an average for the entire month or week. The September 25 column is a dated snapshot, not a live rate feed.
These national benchmarks provide context for Florida buyers. Your available rate depends on your actual credit, down payment, property, loan details, points, lender and lock terms. This is not a claim that every borrower can obtain these rates.
| 30-year fixed loan | Aug. 25, 2026 | Sept. 18, 2026 | Sept. 25, 2026 |
|---|---|---|---|
| Conventional | 6.74% | 7.20% | 7.49% |
| FHA | 6.32% | 6.81% | 7.17% |
| VA | 6.34% | 6.82% | 7.19% |
Payment comparison: conventional, FHA and VA
Each row assumes a $300,000 loan balance, 360 monthly payments, full amortization and a fixed interest rate. The loan amount is not the home’s purchase price. The only input changed within each row is the interest rate.
No financed FHA upfront mortgage insurance premium or VA funding fee is added to the balance. Taxes, property insurance, flood insurance, mortgage insurance, association charges and closing costs are excluded. Actual financing may include additional costs and a larger balance.
| 30-year fixed loan | Aug. 25 monthly P&I | Sept. 18 monthly P&I | Sept. 25 monthly P&I | Change since Aug. 25 | Change since Sept. 18 |
|---|---|---|---|---|---|
| Conventional | $1,943.80 | $2,036.36 | $2,095.59 | +$151.79 | +$59.23 |
| FHA | $1,860.83 | $1,957.77 | $2,030.28 | +$169.44 | +$72.50 |
| VA | $1,864.75 | $1,959.77 | $2,034.33 | +$169.59 | +$74.56 |
How much does that difference matter?
Compared with August 25, the conventional example costs $151.79 more per month in principal and interest. FHA is $169.44 higher and VA is $169.59 higher. Compared with September 18, the respective changes are $59.23, $72.50 and $74.56 per month. Calculations use unrounded payments, then round the results; subtracting already-rounded display figures can differ by a cent.
Those differences may be manageable for one household and decisive for another. They measure these particular dates, not the entire increase someone may face compared with a much older quote or a substantially lower rate.
At the same term and rates, the dollar difference scales with the loan amount. A $200,000 loan would have about two-thirds of the illustrated change; a $400,000 loan would have about four-thirds. Your own loan amount is therefore essential to the discussion.
Why the lowest rate does not automatically mean the lowest cost
Loan programs have different qualification rules and cost structures. Obtain comparable Loan Estimates before selecting a program. Sources: CFPB loan options and VA funding fees.
- Conventional: include private mortgage insurance if it applies, alongside points and other loan costs.
- FHA: include applicable upfront and annual mortgage insurance. A lower note rate can still produce a higher overall payment or cost.
- VA: available only to eligible borrowers. VA loans do not require monthly mortgage insurance, but a funding fee may apply unless the borrower qualifies for an exemption. Financing the fee increases the balance.
Should Florida buyers keep renting because rates increased?
It is reasonable to pause and check the numbers. Renting may be the better fit when you need flexibility, expect to move soon, or would have too little cash left after buying. Buying may be worth evaluating when the complete payment fits your budget, you have reserves and the home supports your plans.
Compare similar homes in the same area and use current written figures. Rent covers use of the property, while ownership brings expenses and responsibilities beyond the mortgage. Neither a rent payment nor a principal-and-interest figure tells the whole story.
| Compare | Renting | Owning |
|---|---|---|
| Monthly cash outflow | Rent, renters insurance, applicable fees and utilities | Principal and interest, taxes, insurance, mortgage insurance, HOA/condo charges and maintenance |
| Upfront cash | Deposit, moving costs and applicable lease fees | Down payment, closing costs, prepaid items, moving costs and reserves |
| Time horizon | Lease terms and possible renewal changes | Purchase and eventual selling costs, upkeep and length of ownership |
| Uncertainty | Future rent and renewal terms are not guaranteed | Future home value, resale timing and refinancing are not guaranteed |
The Florida expenses that need their own estimates
Use property-specific homeowners insurance and flood-insurance quotes where relevant. Estimate property taxes for your purchase rather than assuming the seller’s bill will be yours. Review association dues, assessments, maintenance needs and cash remaining after closing.
The interest-rate change is only one input. The home’s other expenses may change the decision more substantially. The CFPB Loan Estimate explainer identifies projected payments and costs paid outside escrow. Our Martin County full-payment guide and St. Lucie County homebuyer guide apply that approach locally.
What if you already own a home?
If you have a standard fixed-rate mortgage, a Fed hike does not reset your note rate. Your total payment can still change because of taxes, insurance or other charges. An ARM follows its own index, margin, adjustment dates and caps. CFPB loan-type explanation.
If an ARM adjustment is approaching, review the servicer’s notice and your contract before deciding whether refinancing helps. Our ARM reset and refinance explainer covers the calculation and tradeoffs.
How to compare a quote without guessing about next week
There is no rate forecast in this article. The useful question is whether the available payment and terms fit your situation now. Our buy-or-rent guide can help organize that review.
- Compare the same loan amount, loan type, repayment term and rate-lock period.
- Review the interest rate, APR, points, lender credits and cash to close together.
- Confirm whether the quote is locked and when the lock expires.
- Compare the full monthly housing cost with a realistic rental alternative and your other obligations.
Florida mortgage rates and rent-versus-buy questions
Frequently asked questions
Did the Fed raise mortgage rates by exactly 0.25 percentage point?
No. The Fed raised its short-term policy target by that amount. Mortgage rates are separately priced and do not move in a guaranteed one-for-one relationship.
Are these Florida mortgage rate quotes?
No. These are dated national Mortgage News Daily benchmarks used for an educational payment comparison. A Florida borrower needs a personalized quote.
Does the comparison include insurance and taxes?
No. It shows principal and interest only. Taxes, insurance, mortgage insurance, association charges and other costs need separate estimates.
Is renting automatically better when rates rise?
No. The answer depends on the complete costs of comparable homes, available cash, maintenance needs, time horizon and your budget.
Want to understand your own numbers?
For a personal payment comparison, text “More” to 772-773-2344. Share your target price and planned down payment. Please do not text account numbers or sensitive documents.
Anthony Esposito · Mortgage Loan Originator · NMLS #2831459 · Philanya, Inc. NMLS #2130262. Equal Housing Opportunity. General education, not a loan offer or commitment to lend. Qualification and terms vary.
Primary sources
Program details can change. These links are the starting point for current verification.
- Federal Reserve — September 16, 2026 FOMC statement
- Mortgage News Daily — dated daily index history for August 25, September 18 and September 25, 2026
- Mortgage News Daily — conventional 30-year fixed daily history
- Mortgage News Daily — FHA 30-year fixed daily history
- Mortgage News Daily — VA 30-year fixed daily history
- CFPB — compare loan types
- VA — funding fees and closing costs
- CFPB — Loan Estimate explainer